

November Market Update
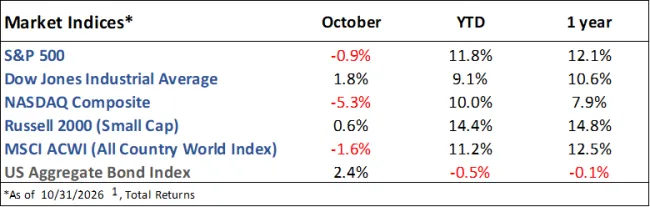
Market Indices Performance
October Recap
The S&P 500 fell -0.9% in October, led lower by the Technology sector after its outperformance in September. This rotation out of tech stocks again coincided with a decrease in bond yields, leading to positive returns for bonds. All major stock indices remain positive YTD.1
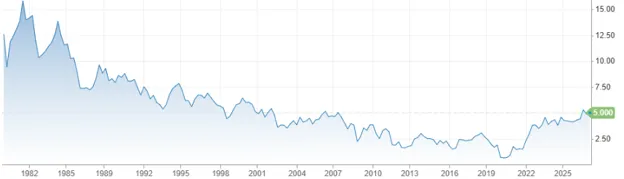
The benchmark 10-year Treasury yield reversed much of September’s increase, falling from 5.29% to 4.93% after climbing above its 2007 peak to a 24-year high (Figure 1).2
Inflation, measured by the Consumer Price Index (CPI), rose 0.4% month-over-month (a year-over-year figure is unavailable due to the government shutdown last October), led again by energy and transportation costs.3
The labor market surprised to the upside in October, as employers added 165k jobs (vs 65k expected), the unemployment rate dipped back from 4.2% to 4.1%, and the labor force participation rate ticked up to 61.9%.3
Current Developments (November)
The midterm elections proved influential for both Washington and the markets, as Democrats gained enough seats to flip both the House and Senate (party control has changed in seven straight midterms).4 The S&P 500 rose over 1.5% the day after the elections but declined 4.4% the next day for its worst day since the tariff-driven selloff in April 2025, as markets seemed to be concerned partly about Democrat politicians tightening restrictions on data centers and the AI buildout.5
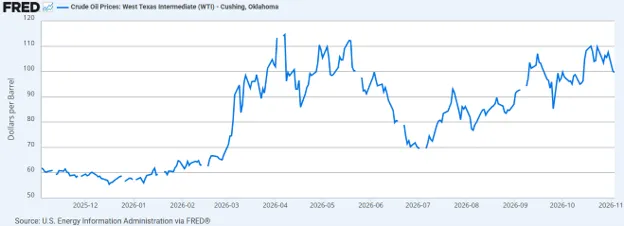
Oil prices have dropped below $90/barrel as President Trump declared the war in Iran “effectively over” and put military strikes on hold after the midterms (Figure 2).6 If this continues, inflation pressures could ease.
The Future
With a Republican president and a Democrat Congress starting in January, gridlock is likely in Washington. Major legislation will need bipartisan support to pass, as Democrat legislation will likely be vetoed by President Trump. Tariffs and other executive actions can still take effect without Congress, at least temporarily.
Historically, a divided government is slightly better than a unified one for markets, likely because the lack of legislation creates more predictability for investors.7 Ultimately, the policies themselves tend to move markets more than which party is in control.
A rate hike is still expected at the Fed’s December meeting, which would bring the federal funds rate to a range of 4.00%-4.25%.8
Investors still expect strong earnings growth for the S&P 500 of 31% in Q3 and 28% in Q4 after 29% growth in Q1 and 52% growth in Q2.9 Whether earnings can outpace the pressure of higher interest rates and inflation remains to be seen.
Historically, November is the best month of the best quarter for the S&P 500, averaging a +1.82% return since 1950.10
1. https://ycharts.com/indices/%5ESPXTR, https://ycharts.com/indices/%5EDJITR, https://ycharts.com/indices/%5ENACTR, https://ycharts.com/indices/%5ERUTTR, https://ycharts.com/indices/%5EMSEAFETR, https://ycharts.com/indices/%5EBBUSATR – Index Performance
2. https://www.cnbc.com/bonds/ - Bond Yields
3. https://www.investing.com/economic-calendar/ - Economic data
4. https://www.dadavidson.com/Perspectives-Insights/Perspectives-Insights-Article/ArticleID/7277/Midterms-Markets-Long-Term-Look-Political-Cycles - Midterm History
5. https://seekingalpha.com/symbol/SP500/historical-price-quotes - S&P 500 daily performance
6.https://www.independent.co.uk/news/world/middle-east/trump-iran-war-midterms-strikes-b3082221.html - Trump Iran Deescalation
7. https://www.usbank.com/investing/financial-perspectives/market-news/stock-market-performance-after-midterm-elections.html - Market Performance by Government
8. https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool – Interest Rate Expectations
9. https://advantage.factset.com/hubfs/Website/Resources%20Section/Research%20Desk/Earnings%20Insight/Earnings Insight_111326.pdf- Earnings
10. https://www.visualcapitalist.com/charted-average-sp-500-return-by-month-since-1950/– Monthly market history
The Gasaway Team
7110 Stadium Drive
Kalamazoo, MI 49009
(269) 324-0080
FAX (269) 324-3834
The views expressed are those of the author as of the date noted, are subject to change based on market and other various conditions. This presentation is not an offer or a solicitation to buy or sell securities. The material discussed is meant to provide general education information only and it is not to be construed as specific investment, tax or legal advice and does not give investment recommendations.
Certain risks exist with any type of investment and should be considered carefully before making any investment decisions. Keep in mind that current and historical facts may not be indicative of future results.
Additional information, including management fees and expenses, is provided on our Form ADV Part 2 available upon request or at the SEC’s Investment Adviser Public Disclosure website, https://adviserinfo.sec.gov/firm/summary/123807.